Facebook
 X
 Pinterest
 Copy Link
Selling With Confidence: The Decisions That Matter Most
Selling a home is one of the biggest financial decisions most people will ever make. While every transaction is unique, I’ve noticed something after completing more than 150 home sales: the sellers who enjoy the smoothest experience aren’t necessarily the ones with the newest homes, the hottest market, or the highest offers.
They’re the ones who make thoughtful decisions before their home ever goes on the market.
There’s rarely one “perfect” way to sell a home. Instead, there are dozens of small decisions that work together to shape your experience and ultimately your results. My goal is never to tell clients what they should do—it’s to help them understand their options so they can make confident decisions that align with their goals.
If you’re thinking about selling, here are some of the decisions that tend to make the biggest difference.
Decision #1: Price Strategically, Not Emotionally
Your home is full of memories.
The market doesn’t know any of them.
That’s not meant to diminish what your home means to you—it simply highlights the difference between emotional value and market value.
One of the most important conversations I have with sellers is about pricing strategy. While everyone hopes to maximize their return, pricing too aggressively can actually reduce buyer interest, increase days on market, and sometimes result in lower offers than if the home had been priced appropriately from the beginning.
Pricing isn’t about guessing.
It isn’t about choosing the highest number that sounds good.
It’s about understanding today’s market, current competition, buyer demand, recent comparable sales, and how buyers perceive value.
That’s exactly why I earned my Pricing Strategy Advisor (PSA) designation. Accurate pricing isn’t about finding one magic number—it’s about creating the strongest opportunity for your home to succeed.
If you’d like to dive deeper into how values are determined, I also discuss this in Why Zestimate Isn’t the Full Story (and What Actually Determines Value).
Decision #2: Prepare Your Home Through a Buyer’s Eyes
One of my favorite questions to ask sellers is:
“If you were seeing your home for the very first time today, what would stand out?”
Often, it’s the little things.
A loose doorknob.
Burned-out light bulbs.
Fresh mulch.
Clean windows.
A freshly painted front door.
Individually, these items may seem insignificant.
Collectively, they shape a buyer’s first impression.
Preparing a home doesn’t mean making it look like a model home or investing thousands into renovations. Instead, it’s about helping buyers focus on everything your home has to offer instead of becoming distracted by things that are easy to address.
This ties directly into something I discussed in The Psychology of Homebuying: How Buyer Perception Shapes Every Showing—buyers don’t simply evaluate a home. They form an emotional impression within minutes.
The goal is helping that first impression work in your favor.
Decision #3: Invest Where It Makes Sense
One question I hear constantly is:
“What should I fix before selling?”
The honest answer?
It depends.
Every home is different.
Every market is different.
Every budget is different.
Sometimes replacing flooring makes perfect sense.
Sometimes a thorough cleaning and fresh paint provide the biggest return.
Sometimes leaving something alone is actually the better financial decision.
Rather than automatically recommending expensive improvements, I prefer evaluating each project through the lens of return on investment, buyer expectations, and your specific goals.
Not every dollar spent before listing automatically increases your sale price.
Smart preparation isn’t necessarily about spending more.
It’s about spending wisely.
Decision #4: Remember That the Best Offer Isn’t Always the Highest Offer
This is one of the biggest misconceptions I see.
The highest purchase price doesn’t automatically equal the best offer.
Every offer is made up of multiple moving pieces:
- Purchase price
- Financing
- Down payment
- Inspection terms
- Appraisal contingencies
- Closing timeline
- Seller concessions
- Occupancy needs
- Overall risk
Sometimes an offer that’s slightly lower on paper creates a smoother closing with fewer unknowns.
Other times, accepting the highest number truly is the best decision.
Every situation is different.
That’s why I encourage sellers to evaluate offers as complete packages instead of focusing on one number alone.
I explore this process more thoroughly in The Art of Negotiation: What Really Happens Behind the Scenes.
Decision #5: Have a Plan for What Comes Next
Selling your current home is only one chapter of the story.
Where are you going afterward?
Are you buying immediately?
Building?
Renting temporarily?
Relocating out of state?
Will you need additional time after closing?
Should you sell first or buy first?
These conversations are often much easier before offers start arriving than once you’re working within contractual deadlines.
Having a plan doesn’t mean every detail is finalized.
It simply means you’ve thought through the possibilities and understand your options.
If you’re trying to balance selling one home while purchasing another, you may also enjoy Should You Sell First or Buy First? Strategy Based on Your Situation.
Decision #6: Choose an Approach That Fits You
Every real estate professional works a little differently.
Some are very hands-off.
Some are highly transactional.
Others focus heavily on communication and education.
There’s no universally right approach.
What’s important is finding someone whose communication style, planning process, and level of guidance align with what you need.
Personally, I believe clients make their best decisions when they understand what’s happening—not when they’re simply told what to do.
That’s why I spend so much time discussing possibilities ranging from the “rainbows and unicorns” scenario all the way to the worst-case scenario. Most transactions fall somewhere in between, but understanding the full picture allows my clients to make decisions with confidence instead of reacting under pressure.
Decision #7: Ask Questions Early—and Often
One of the easiest ways to reduce stress during a sale is surprisingly simple:
Ask questions.
Lots of them.
There are very few bad questions in real estate.
In fact, asking questions early often creates more options.
Whether it’s timing, inspections, repairs, disclosures, pricing, negotiations, or moving logistics, I’d much rather have those conversations before they become urgent.
An informed seller is almost always a more confident seller.
And confidence tends to make every step of the process feel just a little bit easier.
Frequently Asked Questions
When should I start preparing to sell my home?
Ideally, begin planning two to three months before you hope to list. That gives you time to complete repairs, declutter, gather documents, and create a marketing strategy without feeling rushed.
Should I make renovations before selling?
Not always. Some improvements offer an excellent return, while others may not add enough value to justify the expense. The right answer depends on your home, your local market, and your budget.
Is the highest offer always the best offer?
No. Financing strength, contingencies, closing timeline, concessions, and overall risk all play an important role in determining which offer best meets your goals.
How do I know what my home is worth?
The most accurate valuation comes from reviewing recent comparable sales, current market conditions, competition, and buyer demand—not automated online estimates alone.
When should I contact a REALTOR®?
Earlier than most people think. Even if you’re six months away from listing, creating a strategy early often results in better preparation and less stress when it’s time to sell.
Closing Thoughts
Selling a home isn’t about making perfect decisions.
It’s about making informed ones.
Every seller has different priorities. For some, it’s maximizing price. For others, it’s timing, convenience, certainty, or minimizing stress. None of those goals are wrong—they simply require different strategies.
One of the things I enjoy most about working with sellers is helping them understand the choices in front of them so they can move forward with confidence. My role isn’t to make decisions for you. It’s to provide the information, perspective, and strategy that allow you to make the decisions that are right for your situation.
Because when you understand your options, you’re far more likely to enjoy the journey—not just the destination.
The Benefits of Homeownership: How Owning a Home Helps You Build Wealth Over Time
For years, I’ve told buyers something that usually makes them stop and think.
Living in your home is a lot like living in a savings account.
No, I don’t mean your house is a bank. And I certainly don’t mean that home values only go up. Real estate, like any investment, experiences market fluctuations.
What I do mean is this: every month you make a mortgage payment, a portion of that payment is typically reducing your loan balance. You’re gradually increasing your ownership in an asset while also having a place to call home.
Unlike rent—which pays for a place to live but doesn’t create ownership—homeownership gives you the opportunity to build equity over time.
It’s one of the many reasons I believe buying a home can be such a powerful financial tool when it’s the right decision for your goals, budget, and lifestyle.
Homeownership Is About More Than Having a Roof Over Your Head
When most people think about buying a home, they picture the obvious benefits.
A yard for entertaining.
A larger kitchen.
A home office.
A neighborhood they love.
Those things absolutely matter, but they’re only part of the story.
A home is also one of the few purchases you’ll make that has the potential to build wealth while you’re simply living your everyday life.
Every mortgage payment has multiple components. While interest, taxes, and insurance cover various costs, the portion that goes toward your principal is paying down your loan balance. That means your ownership stake in the property grows a little more each month.
Over time, those small monthly gains can become significant.
Understanding Equity
Equity is simply the difference between what your home is worth and what you still owe on your mortgage.
For example:
If your home is worth $450,000 and you owe $300,000, you have approximately $150,000 in equity.
That equity generally grows in two ways:
- By paying down your mortgage principal.
- Through market appreciation when home values increase over time.
Neither happens overnight.
Instead, equity often builds quietly in the background while you’re living your life.
That’s why I tell clients that living in your home is like living in a savings account. Every principal payment increases your ownership, and when appreciation occurs, it can build on top of that foundation.
Wealth Is Usually Built Slowly—Not Overnight
Social media has made it easy to believe wealth happens quickly.
The reality is often much different.
Many of the homeowners I’ve worked with over the years didn’t become financially stronger because they timed the market perfectly.
They became financially stronger because they stayed the course.
They bought a home they could comfortably afford.
They made consistent mortgage payments.
They maintained the property.
They allowed time to work in their favor.
There usually isn’t one dramatic moment.
Instead, wealth often grows through years of small, consistent decisions.
Equity Creates Opportunities
One of my favorite conversations with buyers isn’t about how much they can spend.
It’s about what homeownership may allow them to do years from now.
Because equity creates options.
Over time, homeowners may choose to use their equity to:
- Purchase their next home.
- Move into a different neighborhood.
- Make renovations that improve their quality of life.
- Eliminate private mortgage insurance (PMI) when eligible.
- Consolidate certain debts.
- Invest in another property.
- Supplement retirement planning.
Every person’s situation is different, and equity shouldn’t be viewed as “money to spend.”
Instead, I encourage clients to think of it as flexibility.
Just like I often say purchasing power is about having options—not necessarily spending your maximum budget—the same philosophy applies to equity.
Having options is incredibly valuable.
Your First Home Doesn’t Have to Be Your Forever Home
One of the biggest misconceptions I hear is that buyers need to purchase their forever home first.
I don’t believe that’s true.
Sometimes the smartest financial move is simply buying the right first home.
It may not have every feature on your dream-home checklist.
It may need cosmetic updates.
It may be a condo, townhouse, or a smaller single-family home.
That doesn’t mean it’s the wrong purchase.
In fact, your first home can become the stepping stone that helps make your next home possible.
I’ve seen this happen countless times.
A buyer purchases an affordable starter home.
They build equity over several years.
When life changes, that equity helps provide a larger down payment for the next home.
Without that first purchase, the second opportunity may have been much harder to achieve.
That’s one reason I often encourage buyers to think about today’s decision within the context of tomorrow’s goals.
Appreciation Is Wonderful—But It Isn’t Guaranteed
One of the most important conversations I have with clients is setting realistic expectations.
Real estate markets move.
Values rise.
Values can level off.
Occasionally, values decline.
No one can accurately predict exactly what the market will do in the short term.
Buying a home should never rely solely on the expectation of rapid appreciation.
Instead, I encourage buyers to focus on the factors they can control:
- Purchasing within their comfort level.
- Choosing a home that fits their lifestyle.
- Planning to stay long enough to ride through normal market cycles.
- Maintaining the property over time.
When homeownership is approached with a long-term mindset, temporary market fluctuations tend to become much less intimidating.
Homeownership Offers Emotional Benefits Too
The financial side of buying a home often gets the most attention, but I don’t think we should overlook the emotional side.
Homeownership means creating a space that’s truly yours.
You can paint the walls.
Plant a garden.
Renovate the kitchen.
Celebrate birthdays.
Host holidays.
Those memories matter just as much as the financial benefits.
A house becomes much more than an investment.
It becomes the backdrop to your life.
Renting Isn’t Wrong
I also think it’s important to say something that often gets left out of conversations like this.
Renting isn’t a bad decision.
In fact, for some people, renting is absolutely the right choice.
If you’re planning a short-term move, building your savings, relocating for work, or simply aren’t ready for the responsibilities of homeownership, renting can provide flexibility that buying doesn’t.
The goal isn’t to convince everyone to buy.
The goal is to understand your options and choose the one that best supports your personal and financial goals.
That’s why every conversation I have starts with your situation—not with a sales pitch.
Frequently Asked Questions
Is buying a home still a good investment?
While no investment is guaranteed, homeownership has historically been one of the primary ways many Americans have built long-term wealth through principal paydown and potential appreciation.
How does home equity grow?
Equity generally grows by paying down your mortgage balance and through increases in your home’s market value over time.
Is renting always throwing money away?
Not necessarily. Renting provides flexibility and may be the best choice depending on your financial goals, timeline, and lifestyle.
Can I use equity to buy another home?
Yes. Many homeowners use equity from the sale of one home as the down payment on their next property.
Should I buy my forever home first?
Not always. Many buyers successfully use a starter home as a stepping stone toward future goals.
How long should I plan to stay in a home?
Every situation is different, but buying generally makes more financial sense when you’re planning to stay long enough to offset the costs associated with purchasing and selling a home.
Closing Thoughts
Homeownership isn’t about getting rich overnight.
It’s about creating opportunities over time.
When buying makes sense for your financial situation, your lifestyle, and your long-term goals, a home can become much more than the place where you sleep at night.
It can become one of the strongest financial foundations you ever build.
That’s why I often tell clients that living in your home is like living in a savings account.
Every month you’re not just making a payment.
You’re gradually building ownership in something that’s yours.
And while none of us can predict exactly what the future holds, creating options for tomorrow starts with the decisions we make today.
The Best House Might Be the One Everyone Else Missed
If you’ve spent any time searching for a home, you’ve probably felt it.
A new listing hits the market. Everyone rushes to see it. Showings fill up. Multiple offers start flying around. Emotions take over. Suddenly, buyers who were carefully weighing their options feel pressure to make a decision immediately.
But what if the best house for you isn’t the one attracting all the attention?
What if the best opportunity is actually the home everyone else overlooked?
As a Realtor®, I’ve seen this happen more times than I can count. In fact, some of the happiest homeowners I’ve worked with ended up purchasing homes that had been sitting on the market longer than expected.
Not because there was something wrong with them.
Not because they were a bad investment.
But because the market—and human nature—often causes buyers to focus on what everyone else is chasing rather than evaluating a property on its own merits.
Days on Market Doesn’t Tell the Whole Story
One of the first things buyers notice when browsing online is how long a property has been on the market.
A home listed for three days feels exciting.
A home listed for sixty days can feel suspicious.
The assumption is often that if nobody has purchased it yet, there must be a reason.
Sometimes that’s true.
Many times, it isn’t.
A property may have been overpriced initially and later adjusted.
The marketing may have missed the right audience.
The photos may not have showcased the home’s strengths.
The home may simply have launched during a particularly slow period of the market.
I’ve seen fantastic properties sit while less suitable homes generated bidding wars simply because they were new to the market.
Days on Market is a piece of information. It is not the entire story.
Buyer Psychology Is Powerful
In my blog, The Psychology of Homebuying: How Buyer Perception Shapes Every Showing, we discussed how emotions influence nearly every real estate decision.
Buyers often assume popularity equals value.
If ten people want a house, it must be great.
If nobody is rushing to buy it, there must be a problem.
But that’s not always how real estate works.
Sometimes buyers become focused on competition itself.
The excitement of “winning” can overshadow the more important question:
Is this actually the right house for me?
The goal isn’t to buy the home everyone else wants.
The goal is to buy the home that best supports your lifestyle, finances, goals, and future plans.
Those aren’t always the same thing.
Opportunity Often Lives Where Competition Doesn’t
One of my favorite conversations with buyers happens when we find a property that checks nearly every box but has been sitting on the market.
Instead of immediately dismissing it, we start asking questions.
Why hasn’t it sold?
Is there a material concern?
Is there a location factor?
Was it simply priced incorrectly?
Can we verify concerns through inspections, disclosures, and due diligence?
Many times, the answers reveal opportunity rather than risk.
A home that has been sitting may offer:
- More negotiating power
- Better inspection flexibility
- Greater seller concessions
- Reduced competition
- More time to make thoughtful decisions
- Less emotional pressure during negotiations
That’s not a guarantee, of course.
But it is a reminder that market perception and actual value are not always the same thing.
Looking Beyond First Impressions
One of the biggest challenges in today’s market is that buyers are often making decisions based on a few photos and a quick online impression.
Yet some homes simply don’t photograph well.
Others have cosmetic issues that distract from strong fundamentals.
A bold paint color.
Dated flooring.
Landscaping that needs attention.
Furniture placement that doesn’t showcase the space.
These issues can discourage buyers before they ever walk through the front door.
The reality is that cosmetic issues are often easier and less expensive to address than location, lot quality, floor plan functionality, or structural concerns.
When evaluating a property, I encourage buyers to focus on what can and cannot be changed.
Paint is easy.
Countertops can be replaced.
Furniture leaves.
Location stays.
Lot size stays.
Natural light stays.
The home’s overall layout stays.
Those are often the characteristics that matter most over the long term.
The Difference Between Strategic and Emotional Buying
In another blog, How Much Home Can You Actually Afford vs. What You Should Spend, we discussed the difference between purchasing power and purchasing decisions.
The same concept applies here.
Just because a home is attracting attention doesn’t mean it’s your best option.
Just because a home has been overlooked doesn’t mean it isn’t.
Strategic buyers learn to evaluate opportunities independently of market noise.
They ask:
- Does this home meet my needs?
- Does it align with my budget?
- Does it fit my long-term goals?
- Can I see myself living here for years?
Those answers matter far more than how many other buyers have toured the property.
Sometimes the Best Stories Start Unexpectedly
Over the years, I’ve watched buyers walk away from homes they initially dismissed, only to regret it later.
I’ve also watched buyers reluctantly agree to see a property that had been sitting on the market, fall in love with it, negotiate favorable terms, and ultimately end up in a home they still rave about years later.
Real estate is full of surprises.
The home that appears perfect online isn’t always the right fit.
The home that gets overlooked isn’t always flawed.
Sometimes it’s simply waiting for the right buyer to recognize its value.
FAQs
Should I avoid homes that have been on the market a long time?
Not necessarily. A longer market time is a signal to investigate further, not automatically eliminate the property. Understanding why a home hasn’t sold is often more important than the number of days it has been listed.
Can a home sitting on the market be a red flag?
It can be, but not always. Pricing, marketing, timing, condition, and buyer perception can all influence market time. Proper due diligence helps separate actual concerns from perceived ones.
Do sellers become more negotiable after a home has been on the market for a while?
Sometimes. Every seller is different, but properties with longer market times may provide additional opportunities for negotiation compared to newly listed homes attracting multiple offers.
How can I tell if a home is a hidden gem?
Focus on fundamentals. Location, layout, lot quality, maintenance history, and overall suitability often matter more than cosmetic imperfections or market popularity.
Is it risky to buy a home that other buyers passed on?
Not automatically. That’s exactly why inspections, disclosures, research, and professional guidance exist. The key is understanding whether buyers passed because of a legitimate issue or simply because of perception.
Closing Thoughts
The best house isn’t always the newest listing.
It isn’t always the one generating the most showings.
It isn’t always the one with the longest line of buyers waiting outside.
Sometimes the best house is the one that gives you room to think.
The one that allows you to negotiate.
The one that quietly checks every box while everyone else is chasing something shinier.
Real estate isn’t about winning a competition.
It’s about finding the right home.
And sometimes, the right home is the one everyone else missed.
The Emotional Side of Buying and Selling a Home (And How to Stay Grounded)
Buying or selling a home is often described as one of life’s biggest financial decisions.
I respectfully disagree.
It’s one of life’s biggest emotional decisions that just happens to involve a lot of money.
The numbers matter. The contracts matter. The inspections, appraisals, financing, deadlines, and negotiations all matter.
But behind every transaction is a person navigating excitement, fear, hope, uncertainty, and sometimes grief—all at the same time.
After helping more than 150 home sales throughout Virginia and West Virginia, I’ve learned something important:
The clients who have the smoothest experience aren’t necessarily the ones with the easiest transactions.
They’re the ones who understand when emotion is helping them—and when it’s starting to make decisions for them.
Let’s talk about why emotions are completely normal, where they tend to show up, and how to keep them from steering the ship.
Why Real Estate Feels So Personal
Unlike buying a car or choosing a new phone, homes become part of our identity.
They’re where birthdays happen.
Where holidays are celebrated.
Where difficult conversations happen.
Where life happens.
Even when you’re buying your very first home, you’re imagining future memories before you’ve even gotten the keys.
That’s why buying and selling often feels so much bigger than the paperwork suggests.
You’re not just purchasing square footage.
You’re making decisions about your future.
Buyers: When Excitement Starts Making the Decisions
One of the biggest emotional traps buyers fall into is confusing excitement with certainty.
You walk into a home.
It feels perfect.
You immediately start imagining furniture placement, holiday decorations, your morning coffee on the porch.
Suddenly…
Everything else disappears.
Sometimes that’s okay.
Sometimes it causes buyers to overlook things they would normally question.
I’ve seen buyers suddenly become comfortable stretching their budget, overlooking inspection concerns, or rushing decisions because they’re afraid of losing “the one.”
This is one reason I encourage clients to think strategically throughout the process—not because I want to remove the excitement, but because I want the excitement to be supported by good decision-making.
As I often tell clients:
Purchasing power isn’t about spending it. It’s about having options.
The same philosophy applies emotionally.
Having options gives you confidence.
Feeling like you only have one option creates pressure.
And pressure rarely leads to great decisions.
Sellers: Your Home Isn’t Just a Product
Selling can be even more emotional.
You’ve likely invested years into your home.
Money.
Time.
Weekend projects.
Landscaping.
Painting.
Repairs.
Memories.
Then buyers walk through and…
…they don’t love your kitchen.
…they comment on the paint color.
…they ask for repairs.
…they offer less than you hoped.
It’s easy for those moments to feel personal.
But they’re usually not.
Buyers aren’t judging your life.
They’re evaluating whether the home fits their life.
That’s a very different conversation.
Separating yourself emotionally from your home—even just a little—can make negotiations dramatically easier.
Negotiations Feel Personal…Even When They Aren’t
Inspection requests.
Repair negotiations.
Price reductions.
Closing cost requests.
Appraisal issues.
These moments can quickly feel like conflict.
In reality, they’re simply another stage of negotiation.
As I discussed in my article on Inspection Negotiations: What’s Reasonable and What’s Not, every buyer has a different comfort level.
Every seller has different priorities.
Neither side is automatically right or wrong.
The goal isn’t to “win.”
The goal is finding a solution both parties can live with.
When everyone remembers that, negotiations become much less stressful.
Fear of Missing Out Is Real
Sometimes buyers become afraid they’ll never find another home.
Sometimes sellers become convinced this is the only buyer they’ll ever have.
Neither is usually true.
Fear creates urgency.
Urgency often creates poor decisions.
I’ve found it’s helpful to pause and ask a simple question:
“Would I make the same decision if I weren’t feeling pressured today?”
That one question has helped many clients slow down long enough to think clearly.
The Danger of Making Decisions on One Bad Day
Every transaction has emotional highs and lows.
One day:
“We got the house!”
The next:
“The inspection found issues.”
The next:
“The appraisal came in.”
The next:
“The lender needs one more document.”
The emotional roller coaster is completely normal.
The mistake is assuming one difficult day defines the entire transaction.
It usually doesn’t.
Many deals that feel stressful halfway through end with happy clients sitting around their new kitchen table a few weeks later.
Logic and Emotion Both Belong at the Table
I don’t believe buying or selling should be emotionless.
Emotion is part of what makes a house become a home.
The goal isn’t to eliminate emotion.
It’s to balance it with information.
That’s why I spend so much time educating clients before they ever have to make a decision.
When emotions inevitably show up, we already have a framework for evaluating options.
I often tell clients we look at everything from the perspective of:
- Best-case scenario
- Most likely scenario
- Worst-case scenario
I jokingly call it my “rainbows and unicorns to worst-case” approach.
Not because I expect the worst.
Because considering the full range of possibilities helps decisions feel less overwhelming.
Trust the Process More Than the Moment
Real estate is full of moments that feel enormous.
A low offer.
An inspection report.
A financing hiccup.
An appraisal.
A delayed closing.
Those moments matter.
But they’re only one chapter of a much larger story.
The best decisions usually come from stepping back, gathering all the facts, and evaluating your options—not reacting to the emotion of the day.
That’s one of the biggest reasons I believe education matters so much throughout the buying and selling process.
When you understand what’s happening and why, uncertainty becomes much easier to manage.
And when you’re grounded, you’re much more likely to make decisions you’ll still feel good about long after closing day.
Frequently Asked Questions
Is it normal to feel anxious when buying a home?
Absolutely. Buying a home involves significant financial and emotional investment. Feeling excited, nervous, or even overwhelmed is completely normal. The key is making decisions based on both facts and feelings rather than emotion alone.
Why do sellers sometimes reject strong offers?
Price is only one piece of the puzzle. Closing timelines, contingencies, financing, repair requests, and certainty of closing all influence a seller’s decision.
How do I avoid becoming emotionally attached too early?
It’s okay to be excited about a home. Just continue evaluating it objectively by considering inspection findings, neighborhood, long-term affordability, resale potential, and how it fits your overall goals.
Why do negotiations sometimes feel so stressful?
Negotiations involve uncertainty, and uncertainty naturally creates emotion. Remember that requests for repairs or concessions are part of the process—not necessarily personal criticism.
Should I walk away if a transaction becomes stressful?
Not necessarily. Nearly every transaction has moments of uncertainty. Before making major decisions, understand what’s actually happening, what your options are, and whether the issue is temporary or truly changes the value of moving forward.
How can a REALTOR® help reduce stress during the process?
A good REALTOR® helps explain what’s happening, prepares you for common challenges, presents your options clearly, and keeps the transaction moving forward without making decisions for you.
Closing Thoughts
Buying and selling real estate will probably never be completely free of emotion—and honestly, I don’t think it should be.
Homes represent chapters of our lives.
They hold memories, dreams, and plans for the future.
The goal isn’t to ignore those emotions.
It’s to make sure they’re accompanied by good information, thoughtful strategy, and enough perspective to make decisions you’ll feel confident about long after closing.
When you stay grounded, you’re far more likely to enjoy the journey—not just the destination.
Moving from Northern Virginia to the Shenandoah Valley: A Realistic Guide
If you’ve spent any time looking at homes in the Shenandoah Valley, you’ve probably had the same reaction many of my clients do:
“Wait… I can get all of that for this price?”
For many buyers relocating from Northern Virginia, the answer is yes. Larger lots, more privacy, mountain views, less traffic, and often significantly more purchasing power can make the Valley incredibly appealing.
But there’s another side to the story.
Moving to the Shenandoah Valley isn’t simply a change of address. It’s a lifestyle shift. And whether you’re relocating from Northern Virginia, New York, Pennsylvania, Ohio, California, or somewhere else entirely, understanding the realities of the region before you move can make the transition much smoother.
As someone who regularly helps relocation buyers throughout Winchester, Frederick County, Clarke County, Warren County, Shenandoah County, Page County, and the surrounding region, I’ve found that the happiest movers are the ones who arrive with realistic expectations—not just excitement.
Let’s talk about what life here is really like.
Why So Many People Are Moving to the Shenandoah Valley
The appeal is easy to understand.
Many relocation buyers tell me they’re looking for:
- More home for their money
- Lower overall cost of living
- Less congestion
- More outdoor recreation
- A stronger sense of community
- Space for hobbies, animals, gardens, or simply breathing room
- Proximity to major metro areas without living in them
For Northern Virginia buyers especially, the Shenandoah Valley often offers an opportunity to upgrade their lifestyle without dramatically increasing their housing budget.
A home that may be unattainable in Fairfax, Arlington, Loudoun, or Prince William County can suddenly become realistic in Winchester, Front Royal, Strasburg, Woodstock, Luray, or other Valley communities.
But affordability is only one piece of the equation.
The Pace of Life Is Different
One of the first things relocation buyers notice is that things simply move differently here.
That’s not good or bad.
It’s just different.
You may find:
- Fewer big-box options nearby
- Longer lead times for contractors
- Different restaurant selections
- More locally-owned businesses
- More community-focused events
- Less emphasis on rushing everywhere
For many people, this becomes one of the things they love most.
For others, it requires an adjustment period.
If you’re used to having every service available within five minutes, the Valley may initially feel slower.
If you’re looking for a little breathing room, it often feels exactly right.
The Commute Matters More Than You Think
One of the biggest mistakes I see relocation buyers make is focusing exclusively on the house while underestimating the commute.
Many buyers moving from Northern Virginia intend to continue working in the metro area.
Before buying, ask yourself:
- How many days per week will I commute?
- What does that drive look like during rush hour?
- What happens if my remote work situation changes?
- How much time am I truly comfortable spending in the car?
A home that feels perfect on a Saturday afternoon can feel very different after several months of commuting.
The goal isn’t simply finding the right house.
It’s finding the right lifestyle.
Rural Living Comes With Rural Responsibilities
Many buyers relocating from urban and suburban areas are excited about acreage.
I understand the appeal.
Mountain views, privacy, and open space are hard to resist.
But rural properties often come with systems buyers may not have encountered before.
Examples include:
- Private wells
- Septic systems
- Propane service
- Gravel roads
- Shared driveways
- Agricultural zoning considerations
- Easements
- Internet availability differences
None of these are necessarily problems.
They’re simply things that require education and understanding.
This is similar to what we discussed in previous blogs about buying across state lines and understanding property-specific considerations before making an offer.
The more informed you are, the better decisions you can make.
Internet and Cell Service Can Be Deal Breakers
This one surprises people.
A lot.
A beautiful property with breathtaking views doesn’t help much if you work remotely and can’t maintain a reliable internet connection.
Before purchasing, buyers should investigate:
- Internet providers
- Available speeds
- Fiber availability
- Cellular coverage
- Future expansion plans
Never assume service availability based solely on the property’s location.
This is especially important for remote workers relocating from larger metropolitan areas.
Weather Feels Different Here
Many relocation buyers love experiencing four distinct seasons.
The Valley offers:
- Beautiful spring blooms
- Warm summers
- Stunning fall foliage
- Winter weather that can vary significantly by location and elevation
However, mountain geography creates unique weather patterns.
A property just a few miles away can experience very different conditions.
Snow removal, road maintenance, driveway accessibility, and travel times may become larger considerations than they were in previous locations.
Community Matters More Than Many Buyers Expect
One thing I consistently hear from relocation clients after they’ve settled in is how quickly they became connected to the community.
The Shenandoah Valley tends to feel smaller and more relationship-driven than many major metro areas.
People often know their neighbors.
Local businesses recognize repeat customers.
Community events draw strong participation.
For many buyers, this becomes one of the most rewarding parts of the move.
Your Purchasing Power May Increase—But Strategy Still Matters
A common misconception is that because homes may be more affordable than Northern Virginia or other high-cost markets, buyers don’t need a strategy.
The opposite is often true.
We’ve discussed this concept in blogs like:
- How Much Home Can You Actually Afford vs. What You Should Spend
- Pre-Approved vs. PreQualification: Why it Matters More Than You Think
Purchasing power creates options.
It doesn’t mean you should automatically spend more.
The strongest relocation buyers approach the process strategically, focusing on long-term goals rather than simply maximizing budget.
Every Area Has Its Own Personality
One of the biggest surprises for out-of-state buyers is how different communities can feel despite being relatively close together.
For example:
- Winchester feels different from Front Royal.
- Front Royal feels different from Luray.
- Luray feels different from Strasburg.
- Clarke County feels different from Frederick County.
Each community offers its own blend of:
- Lifestyle
- Schools
- Amenities
- Commute patterns
- Housing styles
- Lot sizes
- Community culture
This is why I often encourage relocation buyers to spend a weekend exploring before making decisions.
Sometimes the town buyers thought they wanted isn’t actually where they end up feeling most at home.
The Best Move Is the Informed Move
The Shenandoah Valley has become a destination for buyers from Northern Virginia, New York, Pennsylvania, Ohio, California, Maryland, New Jersey, and beyond.
And for good reason.
It’s a beautiful place to live.
But the buyers who are happiest after the move are rarely the ones who focused solely on home prices.
They’re the ones who took time to understand the lifestyle, the communities, the practical realities, and how they wanted their daily lives to look once the boxes were unpacked.
Because moving isn’t just about finding a house.
It’s about finding the right fit.
Frequently Asked Questions
Is moving from Northern Virginia to the Shenandoah Valley common?
Very. Many buyers relocate from Fairfax, Loudoun, Arlington, Prince William, and surrounding areas seeking more space, lower housing costs, and a different pace of life.
Are homes significantly cheaper in the Shenandoah Valley?
Generally speaking, buyers often find greater purchasing power compared to many Northern Virginia markets. However, prices vary significantly by location, property type, acreage, and amenities.
Is remote work possible throughout the Valley?
In many areas, yes. However, internet availability varies considerably, especially in rural locations. Verification should always occur before purchasing.
Do I need special inspections for rural properties?
Potentially. Depending on the property, buyers may wish to evaluate wells, septic systems, water quality, radon, outbuildings, drainage, and other factors.
How far is Winchester from Northern Virginia?
Many parts of Northern Virginia are approximately 60–90 minutes away depending on traffic, destination, and time of day.
Is the Shenandoah Valley a good place to retire?
Many retirees are drawn to the region because of its scenery, recreational opportunities, community atmosphere, and relative affordability.
Closing Thoughts
Whether you’re moving from Northern Virginia or relocating from New York, Pennsylvania, Ohio, California, or anywhere else, the Shenandoah Valley offers something many buyers are searching for: options.
More space. More breathing room. More opportunities to create the lifestyle you actually want.
The key is making sure the move aligns with your goals—not just your budget.
A successful relocation isn’t about finding the cheapest house or the biggest lot.
It’s about finding the place that feels like home.
The Pros and Cons of New Construction vs. Existing Homes
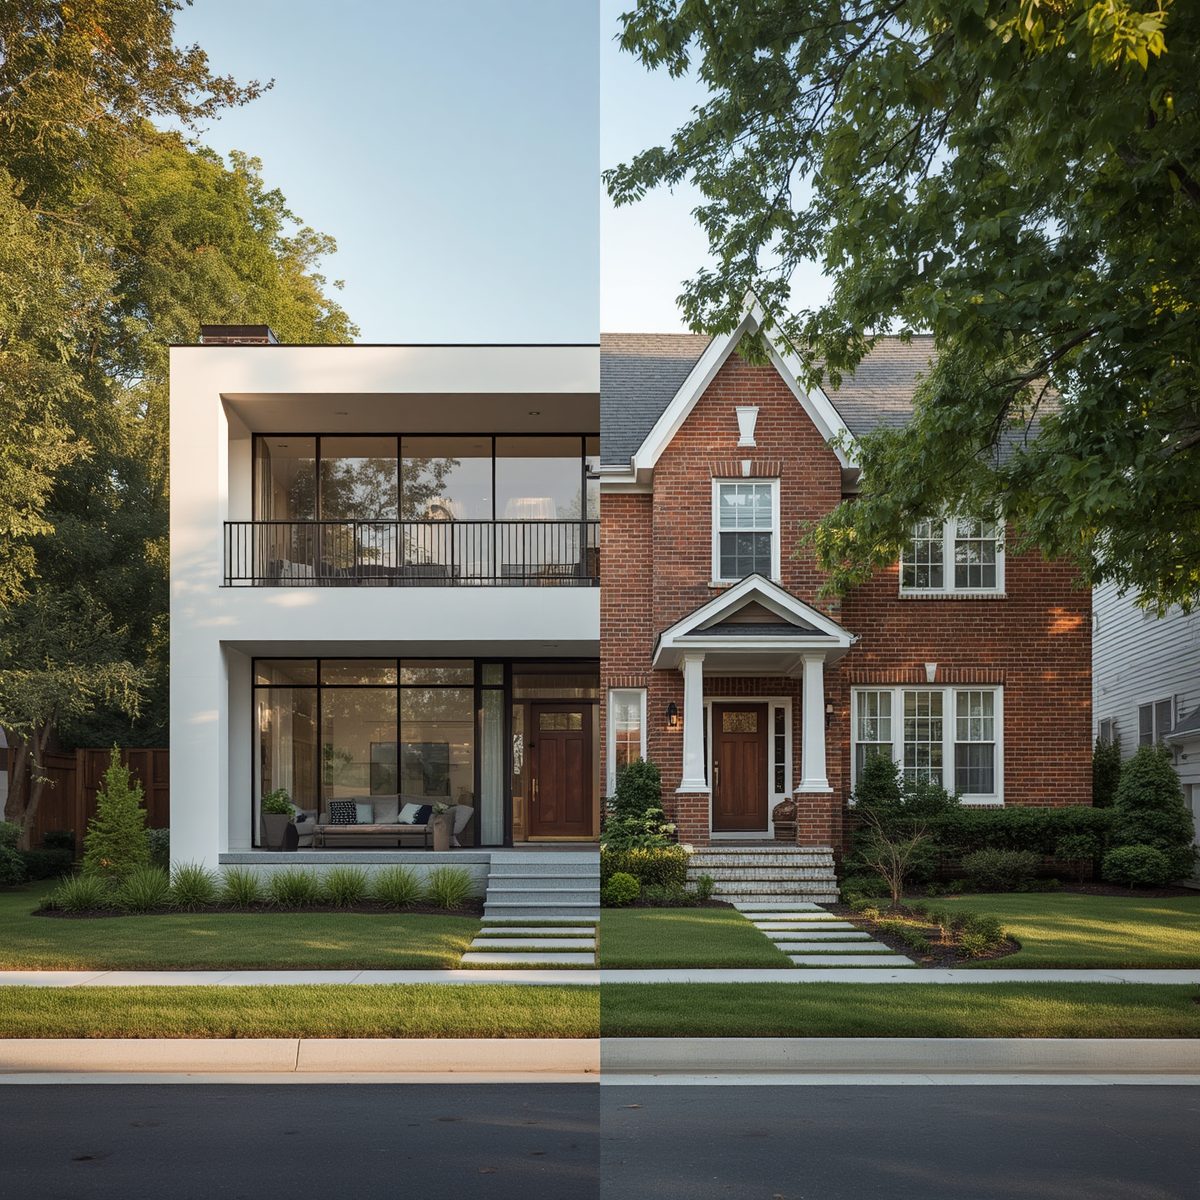
Which one is actually the better investment? The answer might surprise you.
If you’ve started shopping for a home, you’ve probably found yourself asking one of the biggest questions buyers face:
Should I buy a brand-new home or an existing one?
There’s no universal right answer.
I’ve helped clients purchase everything from century-old farmhouses to homes that weren’t even finished being built yet. Both can be incredible opportunities—and both come with challenges many buyers don’t expect.
One of the biggest misconceptions I hear is this:
“If it’s new construction, I won’t have to worry about anything breaking.”
I wish that were true.
The reality is that homes—regardless of age—are built from thousands of individual components. Mechanical systems, appliances, plumbing fixtures, roofing materials, electrical equipment, windows, grading, and countless other parts can experience issues at any point in their lifespan.
The age of a home isn’t what determines whether it’s “good.”
The quality of construction, maintenance, inspections, location, and your expectations matter far more.
Let’s compare both options realistically.
New Construction: The Pros
There are plenty of reasons buyers love new construction.
Modern Floor Plans
Builders design homes around today’s lifestyles.
Open kitchens.
Larger primary suites.
Walk-in closets.
Home offices.
Mudrooms.
These layouts often fit modern living better than homes built decades ago.
Less Immediate Maintenance
Because many components are brand new, buyers often enjoy several years before replacing major systems.
That doesn’t mean nothing can happen—it simply means many items are at the beginning of their expected lifespan.
Builder Warranties
Many builders provide warranties covering various portions of the home for specific periods of time.
These warranties can provide peace of mind—but it’s important to understand exactly what is and isn’t covered.
Personalization
Depending on the stage of construction, buyers may be able to choose:
- Cabinets
- Flooring
- Paint colors
- Fixtures
- Countertops
- Exterior finishes
For many people, designing their home is part of the fun.
Energy Efficiency
New homes often include:
- Better insulation
- Modern HVAC systems
- Energy-efficient windows
- Improved building standards
This can reduce monthly utility costs.
New Construction: The Cons
Brand new doesn’t mean perfect.
In fact, this is where buyer expectations sometimes need adjusting.
New Doesn’t Mean Problem-Free
One of the biggest myths in real estate is that a newly built home doesn’t need an inspection.
Nothing could be further from the truth.
Homes are built by people.
Even excellent builders have subcontractors, timelines, weather delays, material shortages, and human error.
I’ve seen new homes with:
- Inadequate insulation
- Improper grading
- Plumbing leaks or Water Issues
- HVAC issues
- Roofing concerns
- Electrical defects
- Cosmetic workmanship issues
None of these necessarily mean it’s a “bad” home.
It simply means that quality control matters, and that’s exactly why inspections remain an important part of the buying process.
A home being new isn’t a guarantee that it’s perfect.
Additional Costs Can Add Up Quickly
Model homes are beautiful.
They’re also full of upgrades.
The advertised starting price often doesn’t include many of the finishes buyers fall in love with during the design process.
It’s important to budget for:
- Premium lots
- Design center upgrades
- Landscaping
- Window treatments
- Appliances
- Decks or patios
- Fencing
Sometimes those costs surprise buyers.
Construction Timelines Can Change
Building schedules depend on weather, labor availability, inspections, permits, and supply chains.
Closing dates may shift.
If you’re coordinating the sale of another home, timing becomes even more important.
Existing Homes: The Pros
Buying an existing home offers advantages that new construction simply can’t replicate.
Established Neighborhoods
Mature trees.
Landscaped yards.
Walkable communities.
Larger lots.
Neighborhood character develops over decades—not months.
Many buyers value that established feel.
You Know What You’re Buying
An existing home has a history.
You can evaluate:
- Landscaping
- Drainage
- Neighborhood traffic
- Natural light
- Wear patterns
- Previous improvements
Rather than imagining what everything will look like, you can experience it firsthand.
Potentially Better Value
Sometimes existing homes offer:
- More square footage
- Larger lots
- Better locations
- More mature landscaping
…for a similar price point.
Every market is different, which is why comparing total value—not just list price—is so important.
Existing Homes: The Cons
Older doesn’t automatically mean problematic—but buyers should understand what comes with homeownership.
Maintenance Is Normal
Every home ages.
Roofs wear.
HVAC systems eventually need replacing.
Water heaters don’t last forever.
That’s not a defect.
That’s simply homeownership.
A well-maintained older home can often outperform a poorly maintained newer one.
Renovation Costs
You may eventually choose to update:
- Kitchens
- Bathrooms
- Flooring
- Paint
- Fixtures
The good news?
Many buyers can complete these projects over time while building equity.
Buyer Perception Can Be Misleading
One of my favorite conversations with buyers centers around perception.
People often assume:
New equals perfect.
or
Older equals expensive.
Neither is necessarily true.
Every home deserves to be evaluated individually.
I’ve seen immaculate 70-year-old homes.
I’ve also seen brand-new homes with inspection reports several pages long.
That’s why I encourage clients to avoid making decisions based on assumptions.
Instead, we evaluate:
- Condition
- Construction quality
- Inspection findings
- Maintenance history
- Future costs
- Long-term goals
Because those factors tell us much more than the year the home was built.
The Right Home Depends on You
There isn’t a universally “better” choice.
Some buyers prioritize:
- Low maintenance
- Customization
- Energy efficiency
Others prioritize:
- Character
- Larger lots
- Established neighborhoods
- Mature landscaping
Neither is wrong.
It’s simply about matching the home to your lifestyle—not someone else’s expectations.
Strategy Beats Assumptions
One thing I often remind buyers is this:
Every house was new construction once.
Age alone doesn’t determine quality.
Preparation does.
Inspections do.
Maintenance does.
And having realistic expectations does.
Whether you’re buying a home built last week or last century, your goal should be the same:
Understand what you’re buying so you can make a confident, informed decision.
That’s where strategy always wins.
Frequently Asked Questions
Should I still get a home inspection on a new construction home?
Absolutely. New homes can have defects just like older homes. An independent home inspection helps identify issues before closing and gives buyers valuable information about their investment.
Are older homes more expensive to maintain?
Not necessarily. A well-maintained older home can require fewer repairs than a newer home with poor workmanship or deferred maintenance. The home’s condition matters more than its age.
Is new construction more expensive?
It depends. Builder upgrades, premium lots, landscaping, appliances, fencing, and window treatments can significantly increase the final purchase price beyond the advertised base price.
Which appreciates faster?
Both new construction and existing homes can appreciate well. Appreciation is influenced more by location, market conditions, inventory, and demand than by whether the home is brand new.
Which is better for first-time buyers?
There’s no one-size-fits-all answer. Some first-time buyers prefer the predictability of new construction, while others find better value, established neighborhoods, or larger lots in resale homes.
Closing Thoughts
One of the most rewarding parts of my job is helping buyers look beyond assumptions and evaluate homes objectively. New construction isn’t automatically the better choice, and an older home isn’t automatically a risky one. Every property has its own story, strengths, and considerations.
Just as I discussed in “The Psychology of Homebuying: How Buyer Perception Shapes Every Showing,” our expectations can influence how we see a home before we’ve truly evaluated it. Pairing that mindset with the strategies from “Inspection Negotiations: Focusing on What Really Matters“ and “What ‘As-Is’ Really Means (for Buyers and Sellers)“ helps buyers move past myths and make decisions based on facts instead of fear.
My goal is never to convince you that one option is better than the other. It’s to help you understand the differences, ask the right questions, and choose the home that best fits your goals—whether it was built this year or a hundred years ago.
Best Realtor in Winchester VA? Why So Many Buyers and Sellers Choose Nicole Lewis Real Estate
If you’re searching for the best Realtor in Winchester, VA, you’re probably not looking for a list of agents.
You’re looking for someone you can trust.
Someone who understands the local market.
Someone who communicates clearly.
Someone who will answer the phone when things get stressful.
Someone who can explain the process and help you make confident decisions.
The truth is, there isn’t one single “best” Realtor for everyone. The right fit depends on your goals, communication style, timeline, and the level of guidance you’re looking for throughout the process.
For many buyers and sellers throughout Winchester, the Shenandoah Valley, and the Eastern Panhandle of West Virginia, that Realtor is Nicole Lewis.
Why Buyers and Sellers Choose Nicole Lewis Real Estate
For more than seven years, Nicole Lewis has helped over with over 150 home sales and purchases throughout Virginia and West Virginia, facilitating over $50 million in real estate sales volume along the way.
As a dual-licensed Realtor serving both Virginia and West Virginia, Nicole helps between an approfamilies each year navigate one of the biggest financial decisions of their lives.
She serves clients throughout:
Virginia
- Winchester
- Frederick County
- Clarke County
- Warren County
- Shenandoah County
- Page County
West Virginia
- Berkeley County
- Jefferson County
- Morgan County
- Hampshire County
- Hardy County
But numbers only tell part of the story.
What truly sets Nicole Lewis Real Estate apart is a philosophy built around education, preparation, communication, and advocacy.
Her business is guided by a simple principle:
Your Goals. Strategic Guidance. Empowered Decisions.
Every recommendation, pricing discussion, negotiation strategy, and showing is built around helping clients make informed decisions—not simply completing another transaction.
Experience Beyond Real Estate
Before becoming a Realtor, Nicole spent nearly two decades in New York City’s hospitality industry, where she trained hundreds of employees and learned the value of exceptional service, communication, and problem-solving.
That background still shapes the way she approaches real estate today.
Clients are never treated like transaction numbers.
Questions are encouraged.
Communication is prioritized.
And every client receives the same level of care whether they’re purchasing their first home, selling a luxury property, relocating across state lines, or planning for retirement.
A Realtor Who Will Tell You the Truth
One of the most common compliments Nicole receives is that she isn’t afraid to have difficult conversations.
If a buyer is settling for a house that doesn’t align with their long-term goals, she’ll say so.
If a seller’s expectations don’t align with current market conditions, she’ll explain why.
Nicole often says that she isn’t a “yes person,” but her clients quickly learn that’s one of her greatest strengths.
Her responsibility isn’t to tell clients what they want to hear.
It’s to help them make decisions they’ll feel confident about years after closing.
That philosophy has become the foundation of her business and one of the reasons so many clients return and refer friends and family.
Strategic Guidance Creates Better Results
Many people assume real estate success comes down to luck or timing.
Nicole sees it differently.
She believes preparation creates opportunity.
For sellers, that means discussing pricing strategy, buyer perception, marketing, negotiation, and property presentation before a home ever hits the market.
In fact, if you’ve read her article, “Why Zestimate Isn’t the Full Story (And What Actually Determines Value),” you’ll know that pricing a home involves far more than an online estimate. Buyer perception, market conditions, competing inventory, and presentation all influence value.
As a Pricing Strategy Advisor (PSA) certified Realtor, Nicole helps sellers understand those factors and develop a strategy designed to maximize both interest and value.
For buyers, strategic guidance means evaluating homes through both an emotional and practical lens.
Nicole often reminds clients that purchasing power isn’t about spending every dollar a lender approves. It’s about having options and making decisions that align with long-term goals.
Education First, Always
One of the most consistent themes throughout Nicole’s client reviews is education.
Tim, a recent seller, shared:
“Nicole was absolutely the best realtor I’ve worked with and I’ve worked with a few. She walked me through every step of the way when I was selling my home and always made sure I understood every process.”
That educational approach extends to every stage of a transaction.
Whether explaining financing concepts covered in “Pre-Approved vs. PreQualification: Why it Matters More Than You Think,” helping clients understand inspection negotiations, or walking through contract terms, Nicole believes informed clients make better decisions.
Questions are never an inconvenience.
They’re part of the process.
Helping Buyers Find the Right Home, Not Just Any Home
One thing clients quickly discover is that Nicole isn’t focused on simply getting someone under contract.
She’s focused on helping them find the right home.
If you’ve read “The Psychology of Homebuying: How Buyer Perception Shapes Every Showing,” you’ve already seen how emotions influence buying decisions.
Nicole helps clients balance those emotions with practical considerations so they don’t confuse excitement with the right decision.
That approach often requires patience.
It also leads to better outcomes.
Kevin Strasburg experienced this firsthand:
“In a market that had few houses available, Nicole took our requirements and steered us to the home that met all our requirements.”
Helping clients avoid settling is one of the most important parts of Nicole’s job.
Negotiation Is More Than Winning
Another area where Nicole’s clients consistently benefit is negotiation.
Negotiation isn’t about beating the other side.
It’s about helping clients achieve the best possible outcome while keeping a transaction moving toward the finish line.
Whether negotiating price, repairs, appraisal concerns, inspections, or contract terms, Nicole focuses on practical solutions and informed decision-making.
As discussed in her article, “The Art of Negotiation: What Really Happens Behind the Scenes,” some of the most important negotiations happen long before either side realizes they’re occurring.
Preparation, communication, and understanding motivations often matter more than aggressive tactics.
Local Expertise Matters
Real estate is local.
Very local.
What’s happening in Winchester may be entirely different from what’s happening in Front Royal.
What’s happening in Martinsburg may not reflect what’s happening in Berkeley Springs.
As a full-time Realtor serving Winchester, Frederick County, the Shenandoah Valley, and the Eastern Panhandle, Nicole provides insights that extend beyond online estimates and national headlines.
This local expertise is especially valuable for relocation buyers.
Tania Walker relocated from North Carolina and shared:
“Nicole was wonderful to work with and was quick to identify houses that met our needs, including the one we moved into recently. She is very knowledgeable about Winchester, including services and amenities.”
For buyers evaluating both Virginia and West Virginia, Nicole’s dual-state licensing creates a seamless experience that few agents can offer.
What Clients Have to Say
Jeff Thomas shared:
“Nicole guided us in developing a strategy to get us our target sale price, actually helping us gain much more than we hoped. She aggressively worked to sell our home with a sound marketing strategy.”
Samantha Hall shared:
“As first-time home buyers the process was a lot to say the least. Everything was new and scary and stressful. Nicole was extremely patient, kind, understanding, and so incredibly helpful throughout the whole process.”
Haley Clements shared:
“From the very beginning, she demonstrated professionalism, deep market knowledge, and genuine care for our needs. She was always available to answer our questions, kept us informed every step of the way, and made the entire process smooth and stress-free.”
Andrew Clements perhaps summed it up best:
“Bought and sold with Nicole. Talked us off a ledge a few times. Nicole got us the maximum value out of our house. Kept the stress as low as possible.”
The Results Speak for Themselves
Over the past seven years, Nicole Lewis has:
- Helped more than 150 homes to be sold or purchased
- Facilitated approximately $50 million in sales volume
- Maintained a full-time real estate practice serving Virginia and West Virginia
- Earned a reputation built on education, advocacy, and communication
- Consistently helped an average of approximately 20+ families each year achieve their real estate goals
- Built a business fueled largely by referrals and repeat clients
For buyers and sellers searching for the best Realtor in Winchester, VA, those numbers represent more than transactions.
They represent relationships, trust, and families successfully achieving their goals.
Frequently Asked Questions
Is Nicole Lewis one of the top Realtors in Winchester, VA?
Many buyers and sellers choose Nicole Lewis because of her local expertise, educational approach, proactive communication, negotiation skills, and commitment to helping clients make informed decisions. The best Realtor ultimately depends on your goals and preferred working style.
How many families has Nicole Lewis helped buy and sell homes?
Nicole has helped with more than 150 home buying and selling experiences throughout Winchester, the Shenandoah Valley, and the Eastern Panhandle during her seven-year real estate career.
Is Nicole licensed in both Virginia and West Virginia?
Yes. Nicole Lewis is dual licensed in Virginia and West Virginia, helping buyers and sellers navigate transactions seamlessly across state lines.
What areas does Nicole Lewis serve?
Nicole serves Winchester City, Frederick County, Clarke County, Warren County, Shenandoah County, Page County, Berkeley County, Jefferson County, Morgan County, Hampshire County, and Hardy County.
What makes Nicole Lewis different from other Realtors in Winchester, VA?
Clients frequently cite Nicole’s communication, education-first approach, responsiveness, honest advice, negotiation skills, and proactive guidance as reasons they choose to work with her.
Does Nicole work with first-time homebuyers?
Absolutely. Nicole has extensive experience helping first-time buyers understand financing, navigate contracts, evaluate homes, negotiate effectively, and move forward with confidence.
Closing Thoughts
The best Realtor in Winchester, VA isn’t necessarily the one with the biggest billboard, the most advertisements, or the loudest marketing.
It’s the one who understands your goals, communicates clearly, provides honest guidance, and helps you make confident decisions.
For more than 150 transactions throughout Winchester, the Shenandoah Valley, and the Eastern Panhandle of West Virginia, that Realtor has been Nicole Lewis.
If you’re considering buying, selling, relocating, or simply exploring your options, the next step isn’t another Google search.
It’s a conversation.
Inspection Negotiations: What’s Reasonable, What’s Not, and Why It Depends
Buying a home is exciting, but there’s one part of the transaction that can quickly become emotional for everyone involved: the home inspection.
I’ve heard buyers ask, “Should we ask for this?”
I’ve heard sellers wonder, “Are they really expecting me to fix all of that?”
The truth is, inspection negotiations aren’t about right or wrong. They’re simply another stage of negotiation. Every buyer has a different comfort level, every seller has different priorities, and every home has its own story.
There isn’t a universal checklist that determines what’s “reasonable.” Instead, successful inspection negotiations happen when both parties understand the bigger picture and work toward a solution they can both accept.
The Inspection Isn’t a Pass or Fail Test
One of the biggest misconceptions about home inspections is that they’re designed to determine whether a house is “good” or “bad.”
They’re not.
A home inspection is simply a snapshot of the property’s condition on a particular day. Every home—even new construction—will have findings.
Some will be routine maintenance items.
Some will be cosmetic.
Some may point to larger concerns involving the home’s systems or structure.
The inspection doesn’t decide whether you should move forward. It simply gives you more information so you can make an informed decision.
That’s why I’ve always believed education is more valuable than emotion during this part of the process.
There Isn’t One “Correct” Inspection Request
This is something I stress with every client.
In both Virginia and West Virginia, inspection negotiations ultimately come down to purchaser discretion. No one—not your REALTOR®, not the seller, not the inspector—can decide what level of risk or comfort is appropriate for you.
What one buyer views as a deal breaker, another buyer may barely notice.
One family may happily purchase a home needing a new HVAC system because they planned renovations anyway.
Another buyer may not feel financially comfortable taking that on immediately after closing.
Neither perspective is wrong.
The important part is understanding your options and making decisions that align with your goals.
Why I Encourage Clients to Focus on Systems and Structure
Although every buyer has the right to request whatever concerns them, I often encourage clients to focus their negotiations on items involving the home’s major systems, structural integrity, or safety.
That doesn’t mean cosmetic items don’t matter.
It simply means there’s often a practical strategy behind prioritizing bigger concerns first.
Think about things like:
- Roofing concerns
- Foundation issues
- Electrical hazards
- Plumbing leaks
- HVAC failures
- Moisture intrusion
- Significant structural defects
These types of issues can be expensive, affect the home’s function, or create larger problems over time.
There’s another important consideration that many buyers don’t realize.
If significant defects are identified and negotiations fall apart, the seller may have disclosure obligations regarding those material defects in future transactions, depending on state law and the circumstances involved.
Because of that, sellers often have additional incentive to thoughtfully consider requests involving substantial issues.
That doesn’t guarantee they’ll agree.
It simply explains why negotiations surrounding major systems and structural concerns sometimes have a different dynamic than requests involving smaller cosmetic items.
Cosmetic Doesn’t Mean Unimportant
This is where I try to avoid blanket advice.
Minor scratches.
Loose cabinet pulls.
Paint touch-ups.
Small drywall repairs.
Sticky doors.
These things might feel important to one buyer and completely insignificant to another.
And that’s okay.
Sometimes those items become part of a larger conversation.
Sometimes buyers simply decide they’ll handle them after closing.
Sometimes sellers happily agree because they’re relatively inexpensive.
There isn’t a universal answer.
The goal isn’t to decide whether something is “worthy.”
The goal is deciding what matters most to you.
Every Seller Is Different, Too
Just as every buyer has a different comfort level, every seller approaches negotiations differently.
Some sellers would rather make repairs than renegotiate pricing.
Others prefer offering a credit.
Some are unable—or simply unwilling—to complete repairs before closing.
Others may have already priced the home knowing it would need updates.
This is why predicting inspection negotiations is nearly impossible.
No two sellers respond exactly alike.
The strongest strategy is approaching negotiations with realistic expectations, good information, and a willingness to have productive conversations.
Negotiation Is About Finding Common Ground
Inspection negotiations aren’t about “winning.”
They’re about determining whether both parties can reach an agreement they’re comfortable with.
Sometimes that’s repairs.
Sometimes it’s a credit.
Sometimes it’s adjusting the purchase price.
Sometimes it’s agreeing that no additional action is needed.
And occasionally, the answer is that both parties simply can’t come together.
While that’s disappointing, it’s also okay.
Not every transaction is meant to make it to the closing table, and forcing a deal rarely benefits anyone in the long run.
A Team Approach Makes a Difference
This is one of the reasons I spend so much time preparing clients before we ever receive an inspection report.
I don’t want anyone making decisions based solely on emotion.
Instead, we work through each item together, discussing:
- Is this a maintenance item?
- Is this typical for a home of this age?
- Does it affect safety or function?
- Is it likely to become more expensive if ignored?
- Is this something you’re comfortable addressing after closing?
Those conversations help create a strategy that fits each client’s goals instead of relying on generic advice from the internet.
It’s the same approach I discussed in The Art of Negotiation: What Really Happens Behind the Scenes. Every negotiation is different because every client is different.
Likewise, understanding What “As-Is” Really Means (For Buyers and Sellers) helps set realistic expectations before inspection negotiations even begin, while The Top Reasons Deals Fall Apart (And How to Avoid Them) highlights how thoughtful communication can keep transactions moving forward. And if you’ve read The Psychology of Homebuying: How Buyer Perception Shapes Every Showing, you’ll recognize that buyer perception doesn’t stop once the offer is accepted—it continues throughout the inspection process as well.
Closing Thoughts
Inspection negotiations aren’t about finding the “perfect” house.
They’re about understanding the home you’re buying and deciding whether its condition matches your comfort level, budget, and long-term goals.
Every buyer deserves to feel confident in their decision.
Every seller deserves a fair opportunity to respond.
When both sides approach the process with realistic expectations and a willingness to communicate, inspection negotiations become what they were always meant to be: another conversation focused on finding common ground.
Having an experienced REALTOR® beside you isn’t about telling you what you should ask for—it’s about helping you understand your options, discuss possible outcomes, and make informed decisions that fit your goals.
Why FSBO Isn’t Always the Money-Saving Move Sellers Think It Is
For Sale By Owner (FSBO) properties have been around for decades, and every year homeowners decide to test the waters without hiring a real estate agent.
On the surface, it makes sense.
If real estate commissions are one of the largest expenses associated with selling a home, why not keep that money in your own pocket?
It’s a fair question.
The reality, however, is that most homeowners quickly discover that selling a home involves much more than putting a sign in the yard, uploading a few photos online, and waiting for buyers to arrive.
As someone who works with sellers throughout Virginia and West Virginia, I’ve seen both sides of the equation. Some homeowners successfully sell on their own. Many more eventually hire an agent after realizing how much time, expertise, strategy, and risk management is involved.
The goal isn’t to convince everyone that FSBO is impossible.
It’s to help sellers understand what they’re truly taking on before deciding to go it alone.
Why Homeowners Choose FSBO
Most FSBO sellers start with good intentions.
Common reasons include:
- Saving commission costs
- Believing the market is strong enough to sell without help
- Having experience buying or selling in the past
- Wanting complete control over the process
- Assuming selling a home is relatively straightforward
And to be fair, some parts are straightforward.
Finding a buyer is only one piece of the puzzle.
The challenge is everything that happens afterward.
Selling the Home Is Easy. Managing the Transaction Is Hard
One of the biggest misconceptions about selling a home is that the hard part is finding a buyer.
In reality, finding a buyer is often the easiest part.
Managing everything that happens afterward is where sellers can quickly become overwhelmed.
Once an offer is accepted, you’re suddenly responsible for:
- Contract deadlines
- Earnest money tracking
- Inspection negotiations
- Appraisal issues
- Repair requests
- Title coordination
- Lender communication
- Closing preparation
- Addendums and amendments
- Legal disclosures
Miss a deadline, misunderstand a contingency, or overlook a contractual obligation, and the consequences can become expensive very quickly.
As I discussed in my article, “The Top Reasons Deals Fall Apart (And How to Avoid Them),” many transactions don’t fail because the house won’t sell. They fail because the process wasn’t properly managed.
A REALTOR® doesn’t just help find buyers. They help keep the transaction together once a buyer is found.
Scams Happen More Often Than You Think
Most sellers never consider the security risks associated with selling their home.
Unfortunately, scammers absolutely do.
A few common situations include:
- Fake buyers requesting personal information
- Wire fraud attempts
- Identity theft schemes
- Unauthorized access requests
- Individuals touring homes with no intention of purchasing
- Criminals using showings to gather information about valuables or occupancy patterns
Then there are the “lookie-loos” who simply want to see inside your home with no ability or intention to buy.
A REALTOR® serves as a gatekeeper.
Before someone walks through your front door, there are often conversations, vetting processes, lender verifications, scheduling systems, and accountability measures already in place.
Could a scam still happen?
Absolutely.
But having a professional helping manage access and communications significantly reduces your exposure.
Liability Doesn’t Disappear Just Because You Didn’t Hire An Agent
One of the most overlooked aspects of a FSBO sale is liability.
Many sellers assume they’re reducing costs by removing the REALTOR® from the equation.
What they’re actually doing is assuming responsibility for every decision themselves.
Mistakes happen.
The difference is knowing:
- Which mistakes matter
- How to avoid them
- How to correct them
- How to protect yourself when something goes wrong
Disclosure issues alone can create significant headaches long after closing.
A REALTOR® isn’t there to eliminate every risk.
They’re there to help identify potential problems before they become expensive ones.
Pricing Is Harder Than Most Sellers Realize
One of the biggest challenges for FSBO sellers is determining an accurate list price.
Most homeowners naturally have an emotional attachment to their property.
Unfortunately, buyers don’t.
As discussed in my article, “Why Zestimate Isn’t the Full Story (And What Actually Determines Value),” online estimates are often incomplete because they cannot fully account for:
- Condition
- Upgrades
- Layout functionality
- Market trends
- Buyer demand
- Neighborhood competition
- Property presentation
Pricing too high can cause a home to sit.
Pricing too low can leave money on the table.
Neither outcome is ideal.
This is where market analysis, local expertise, and pricing strategy become invaluable.
As a NAR Pricing Strategy Advisor (PSA), I spend a significant amount of time evaluating not only recent sales but also current competition, buyer behavior, and market conditions before recommending a pricing strategy.
Saving Commission Doesn’t Matter If You Lose More Somewhere Else
The most common reason sellers choose FSBO is simple:
They want to save money.
That’s understandable.
The challenge is that many sellers focus on the commission line item while overlooking all the other ways money can be lost during a transaction.
Potential costs can include:
- Underpricing the property
- Overpricing the property and chasing the market down
- Excessive inspection concessions
- Appraisal issues
- Contract mistakes
- Repair negotiations
- Extended carrying costs
- Additional mortgage payments
- Additional utilities
- Additional insurance costs
- Lost buyer opportunities
Studies have consistently shown that FSBO properties often sell for less than agent-assisted transactions.
Depending on the study and market conditions, that difference can range anywhere from approximately 2% to 16%.
When sellers focus solely on what they might save in commission, they often miss the much larger picture: what they may be losing elsewhere.
Buyers View Homes Differently Than Sellers
One of my favorite topics is buyer psychology.
As discussed in “The Psychology of Homebuying: How Buyer Perception Shapes Every Showing,” perception often becomes reality.
A seller may see:
- Character
A buyer may see:
- Deferred maintenance
A seller may see:
- Cozy
A buyer may see:
- Small
A seller may see:
- Unique
A buyer may see:
- Expensive to update
This doesn’t mean either party is wrong.
It simply means buyers evaluate homes through a completely different lens.
A good agent helps bridge that gap by identifying potential concerns before buyers ever walk through the door.
Marketing Is Limited
Years ago, simply listing a home online could generate significant activity.
Today’s buyers expect much more.
Effective marketing often includes:
- Professional photography
- Floor plans
- Video content
- Social media promotion
- Email marketing
- MLS exposure
- Agent-to-agent networking
- Open houses
- Strategic pricing campaigns
Many FSBO listings receive exposure, but not necessarily maximum exposure.
Through MLS syndication, agent networks, association memberships, automated valuation model integrations, and marketing systems, REALTORS® have access to resources that most homeowners simply don’t.
The more qualified buyers who see your home, the better your chances of creating competition and securing stronger offers.
For Sale By Owner Properties Often Spend More Time on the Market
Time is something many FSBO sellers underestimate.
Even if a home eventually sells, it may take longer to get there.
Without professional marketing, broad exposure, pricing guidance, and established buyer networks, properties can sit on the market longer than anticipated.
Sometimes that’s a week.
Sometimes it’s a month.
Sometimes it’s much longer.
And every additional day on market can create additional carrying costs, additional stress, and additional buyer skepticism.
Time Costs Money Too
One of the hidden expenses of a FSBO transaction is time.
Every phone call.
Every showing.
Every scheduling conflict.
Every inspection appointment.
Every repair estimate.
Every document review.
Every contract amendment.
Every buyer question.
Every lender request.
It all falls on the seller.
Many homeowners already work full-time jobs, have children, family obligations, travel schedules, and countless other responsibilities.
Selling a home can easily become a second job.
A REALTOR® takes much of that workload off your plate, allowing you to focus on your life while still keeping the transaction moving forward.
Because time has value too.
The Paperwork Isn’t Just Paperwork
One of the most dangerous assumptions a seller can make is:
“I’ll just use the contract someone sends me.”
The challenge isn’t accessing the paperwork.
The challenge is understanding it.
Real estate contracts contain:
- Contingencies
- Deadlines
- Notice periods
- Financing terms
- Inspection provisions
- Appraisal language
- Legal obligations
- Default provisions
Once you sign a contract, you’re accountable for what’s inside it.
If you don’t fully understand what you’re agreeing to, you can unintentionally place yourself in a difficult position.
This is one reason why experienced representation can be so valuable.
The paperwork isn’t just paperwork.
It’s the roadmap that governs the entire transaction.
Inspections Can Become Expensive Very Quickly
Most sellers assume inspections are straightforward.
They’re often anything but.
Without understanding what is customary, negotiable, required, or simply a buyer preference, sellers can find themselves agreeing to repairs they may not have needed to make.
I’ve often said:
Everything is negotiable until you get to the closing table.
The challenge is knowing where to negotiate, when to stand firm, and when a concession actually makes sense.
An experienced REALTOR® helps sellers navigate these conversations strategically instead of emotionally.
Sellers Can Get Stuck With a Bad Deal
Another common misconception is that any offer is a good offer.
The reality is that not all contracts are created equal.
Price matters.
But terms matter too.
A higher offer with unfavorable contingencies, unrealistic timelines, weak financing, or excessive demands can ultimately cost a seller more than a lower-priced but stronger offer.
Once a contract is signed, sellers are generally held accountable to what they’ve agreed to.
If you don’t know what to look for, you can easily find yourself stuck dealing with consequences that could have been avoided.
Representation Matters More Than Most Sellers Realize
Perhaps the biggest difference between selling with a REALTOR® and selling without one comes down to a simple question:
Who is looking out for you?
When a buyer has representation and a seller does not, one side of the transaction has a professional advisor helping them navigate every decision.
The other side is left figuring it out as they go.
A REALTOR® provides:
- Strategy
- Guidance
- Negotiation expertise
- Vendor resources
- Market knowledge
- Problem solving
- Risk management
- Transaction coordination
As discussed in “Proactive vs. Reactive Listing Agents: Why the Difference Matters More Than Sellers Realize,” the best outcomes often come from preventing problems before they happen—not simply reacting once they do.
And that’s where professional representation often delivers its greatest value.
FAQs
Can I sell my house without a REALTOR®?
Absolutely. Homeowners have every right to sell their property themselves. The question isn’t whether it’s possible—it’s whether it’s the best strategy for your goals, timeline, and risk tolerance.
Do FSBO homes sell for less?
Many studies have shown that FSBO properties often sell for less than agent-assisted sales. While every situation is unique, sellers should consider the entire financial picture rather than focusing solely on commission savings.
Why do FSBO homes sometimes take longer to sell?
Limited marketing exposure, pricing challenges, and reduced buyer reach can all contribute to longer days on market.
What is the biggest risk of selling a home yourself?
For many sellers, the biggest risks involve contract management, disclosure issues, liability concerns, negotiations, and navigating unexpected problems during the transaction.
Is hiring a REALTOR® worth it?
That depends on your goals and comfort level. For many sellers, the value comes from professional guidance, market expertise, negotiation skills, risk management, and having someone advocating for their interests from listing to closing.
Closing Thoughts
Selling your home is one of the largest financial transactions you’ll ever make.
For some homeowners, FSBO can absolutely work.
But before deciding to go it alone, it’s important to understand that selling a home isn’t just about finding a buyer.
It’s about managing risk, protecting your interests, navigating negotiations, understanding contracts, coordinating timelines, solving problems, and successfully getting to the closing table.
A good REALTOR® isn’t there to take control away from you.
They’re there to provide guidance, strategy, expertise, and support so you can make informed decisions while avoiding many of the costly pitfalls that can arise along the way.
The goal isn’t simply to sell your home.
The goal is to sell it strategically, protect your bottom line, and get to closing with as few surprises as possible.
How Much Home Can You Actually Afford vs. What You Should Spend
One of the most common questions I hear from buyers is:
“How much house can I afford?”
It’s a great question—but I think there’s a better one:
“How much house should I spend?”
Those two numbers are often very different.
When buyers receive their pre-approval letter, it’s easy to view that number as a target. If a lender says you’re approved for $400,000, many people naturally assume they should shop for homes around $400,000.
But that’s not necessarily how I approach the conversation.
In fact, one of the most important discussions I have with buyers is about understanding the difference between purchasing power and spending power.
Because purchasing power isn’t about spending every dollar available to you.
It’s about having options.
What Your Pre-Approval Actually Means
A pre-approval is an important first step in the homebuying process. As we discussed in my previous blog, “Pre-Approved vs. PreQualification: Why it Matters More Than You Think,” a true pre-approval gives buyers a realistic understanding of what financing may be available to them.
However, a pre-approval doesn’t tell you what you must spend.
It simply tells you the range of homes that may be available to you based on your financial qualifications.
Think of it this way:
Your pre-approval is a tool.
It’s not a spending assignment.
And that’s a distinction that can save buyers a lot of stress and help them make better long-term decisions.
Purchasing Power Isn’t About Spending It—It’s About Options
Let’s use a real-world example.
Imagine a buyer is pre-approved for $400,000.
They tell me they’re most comfortable spending around $350,000.
Perfect.
That comfort level matters.
But here’s where many buyers make a mistake.
They immediately want to cap their search at $350,000.
My response is often:
“Why would we eliminate options?”
If we’re approved to $400,000 but hoping to stay around $350,000, I typically encourage buyers to search within the broader range while keeping their desired budget in mind.
Why?
Because what happens if the perfect home appears at $360,000?
The ideal location.
The right floor plan.
The perfect yard.
The right school district.
The features you’ve been searching for during every showing.
Would it make sense to miss that opportunity because we artificially limited our search before seeing what was available?
That’s where purchasing power becomes valuable.
Not because we’re trying to spend more.
Because we’re preserving options.
The Monthly Payment Perspective
One of the exercises I frequently walk buyers through is translating purchase price into monthly payment.
Many buyers see a $10,000 difference in price and assume it’s a massive jump in affordability.
Sometimes it is.
Often it isn’t.
As a rough rule of thumb, every additional $10,000 in purchase price frequently translates to somewhere between $50 and $100 per month in payment, depending on interest rates, taxes, insurance, down payment, and financing terms.
That isn’t a guarantee, and your lender should always provide exact numbers for your situation, as these factors can possibly sway this number even lower or higher.
But it does help create perspective.
Let’s compare:
- Home A: $350,000
- Home B: $360,000
On paper, the difference is $10,000.
Emotionally, that can feel significant.
But when translated into a monthly payment, buyers often realize the actual impact may be much smaller than they expected.
That doesn’t automatically mean spending more is the right answer.
It simply means you’re making a decision based on real numbers instead of assumptions.
Affordability Isn’t Just About the Mortgage
One of the biggest mistakes buyers make is focusing solely on the mortgage payment.
Homeownership includes much more than principal and interest.
There are also:
- Property taxes
- Homeowners insurance
- HOA fees
- Utilities
- Maintenance and repairs
- Landscaping
- Future upgrades and improvements
The larger the home, the larger many of these expenses become.
That’s why I always encourage buyers to think beyond the purchase price and consider their overall financial picture.
This is a topic that also connects nicely to our blog “Real Estate FAQs: Answers to the Questions Buyers and Sellers Ask Most,” because one of the most common questions buyers ask is what their true monthly ownership costs will be after closing.
The answer is almost always more than just the mortgage payment.
Lifestyle Matters More Than Approval Amount
One thing lenders can’t calculate is your lifestyle.
They don’t know:
- How much you enjoy traveling
- Whether you’re saving for retirement
- Business goals
- Hobbies
- Emergency fund preferences
- Future investment plans
Only you know those things.
That’s why I often encourage buyers to establish three different numbers before we start shopping.
Your Comfortable Number
A payment that leaves plenty of room for life.
Your Stretch Number
A payment that still works but requires a bit more planning.
Your Maximum Number
A payment you could comfortably handle if the right home came along.
Notice I didn’t say lender maximum.
I mean your personal maximum.
The number that still allows you to sleep well at night.
The Right House Isn’t Always the Cheapest One
Sometimes buyers assume the smartest financial decision is always choosing the least expensive option.
Sometimes that’s true.
Sometimes it isn’t.
If spending an additional $10,000 or $20,000 means finding a home that better fits your long-term needs, eliminates future moves, provides a superior location, or significantly improves your quality of life, it may actually be the better value.
The key is understanding the tradeoffs.
Not making decisions based solely on list price.
Understanding Your Financing Options
Another reason this conversation matters is because financing choices can dramatically impact affordability.
As discussed in “USDA, FHA, VA, Conventional: Which Loan Actually Fits You Best?“, different loan programs can create very different monthly payment scenarios even at the same purchase price.
The right loan product can increase flexibility, lower monthly costs, and expand your options.
But regardless of the loan type, the goal remains the same:
Use your purchasing power strategically.
Not emotionally.
The Role of a Good Realtor
A good Realtor doesn’t just help you find houses.
A good Realtor helps you evaluate choices.
Part of my job is helping buyers understand the difference between what they can do and what they want to do.
Sometimes that means helping a buyer stay comfortably below their approval amount.
Sometimes it means helping them realize that an extra $10,000 or $20,000 may not have the impact they assumed.
Most importantly, it means helping them make informed decisions based on facts, goals, and long-term plans—not fear or assumptions.
I don’t view purchasing power as a spending target.
I view it as a menu.
The goal isn’t to order the most expensive thing on the menu.
The goal is to understand all of your options before deciding what’s right for you.
Frequently Asked Questions
Should I shop at the top of my pre-approval range?
Not necessarily. Your pre-approval represents available purchasing power, not a required spending amount. Many buyers choose to spend less than their maximum approval while still using the full range to explore their options.
Is it smart to look at homes above my target budget?
Often, yes. Looking slightly above your target budget can help you understand the market and avoid overlooking a home that may ultimately be worth the small difference in monthly payment.
How much does an extra $10,000 typically add to a mortgage payment?
While every loan is different, many lenders estimate that each additional $10,000 in purchase price may add approximately $50 to $100 per month depending on financing terms, taxes, insurance, and current interest rates. Make sure to speak to your lender for the most accurate reply, as there are factors that could sway this number even lower or higher.
Should I spend less than I’m approved for?
That depends on your goals, lifestyle, savings plans, and comfort level. The right answer is different for every buyer.
What’s the biggest affordability mistake buyers make?
Focusing solely on purchase price rather than evaluating the overall monthly financial impact and long-term lifestyle implications.
Closing Thoughts
The question isn’t simply how much house you can afford.
The better question is how much house helps you achieve the life you want.
A pre-approval provides purchasing power.
Purchasing power creates options.
And options create opportunities.
The goal isn’t to spend the most money possible.
The goal is to understand your choices, evaluate them strategically, and make the decision that best supports your long-term goals.
That’s where smart homebuying begins.