Facebook
 X
 Pinterest
 Copy Link
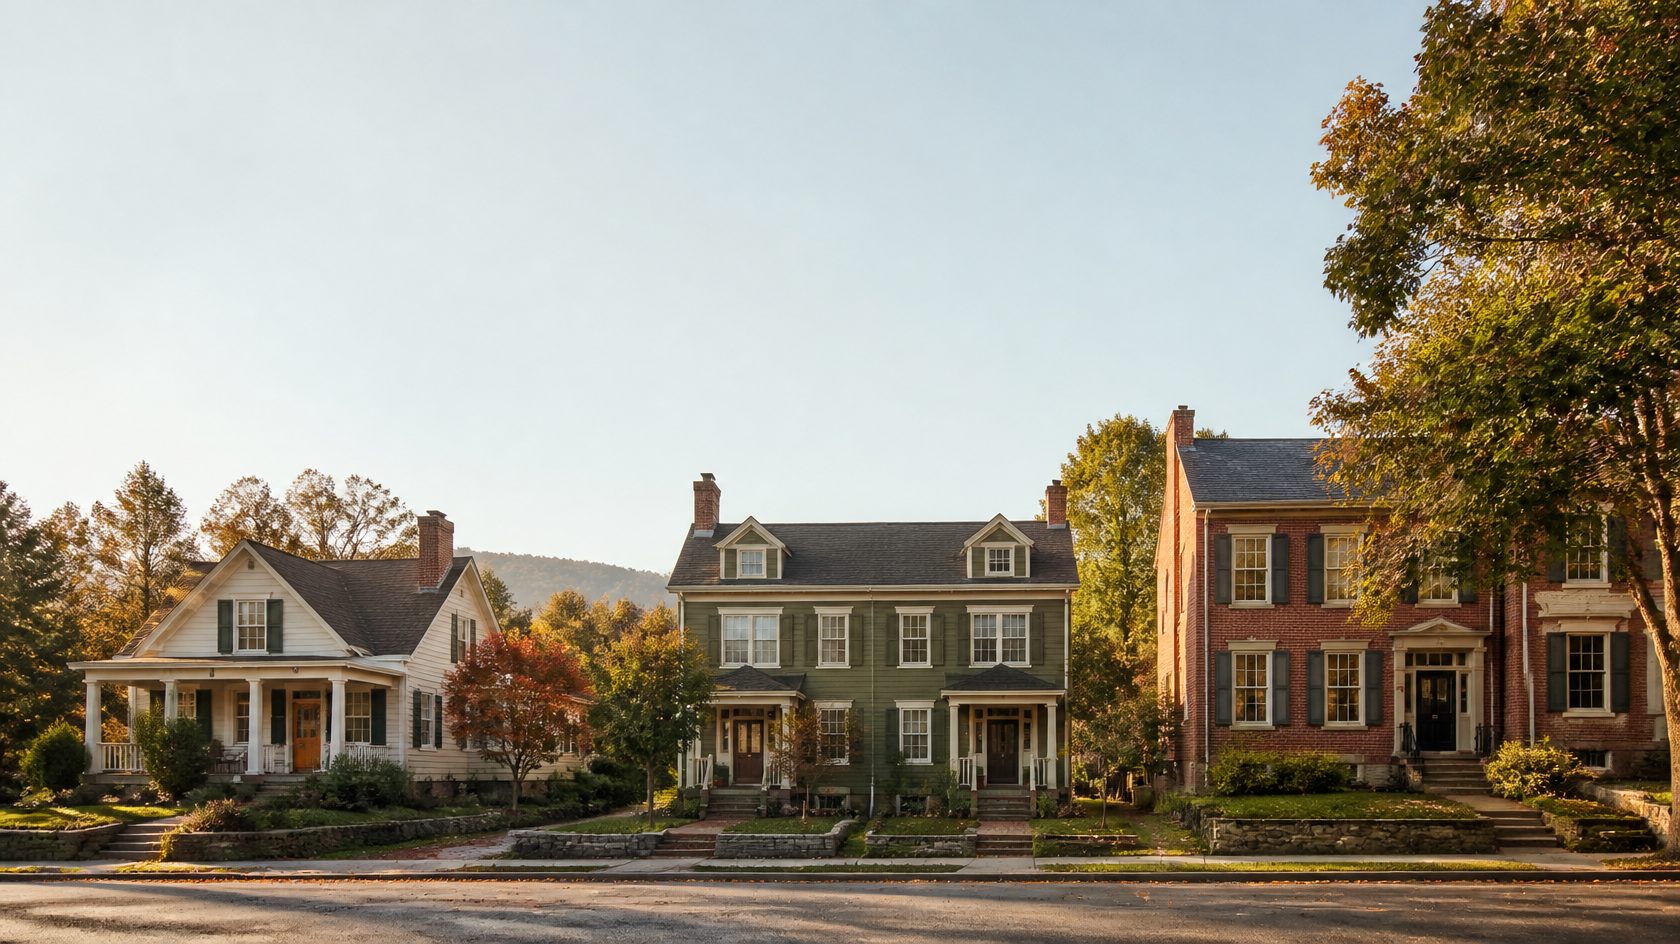
When people think about investing in real estate, they often picture the same scenario: purchasing a second home, finding tenants, and collecting monthly rent.
That’s certainly one approach. But residential real estate investing offers several different strategies, each with its own financial considerations, responsibilities, potential rewards, and risks.
Some investors are interested in generating ongoing income. Others are focused on renovating properties for resale, building equity over time, or finding ways to offset their own housing expenses.
And while these strategies may share certain characteristics, they aren’t interchangeable.
Understanding how different residential real estate investments work—and what they require—is an important first step toward identifying opportunities that align with your goals.
Watch: 5 Ways to Invest in Residential Real Estate
1. Long-Term Rental Properties: Investing for Ongoing Income
One of the most familiar real estate investment strategies involves purchasing a residential property and renting it to tenants under longer-term lease agreements.
These investments might include single-family homes, townhouses, or condominiums. The objective is often to generate rental income while potentially benefiting from property appreciation and mortgage principal reduction over time.
But rental income and positive cash flow aren’t necessarily the same thing.
Mortgage payments, property taxes, insurance, maintenance, vacancies, capital improvements, and property management expenses can significantly affect the financial picture.
An investment property that generates $2,000 in monthly rent isn’t automatically producing $2,000 in income for its owner.
Potential advantages:
- Opportunity for recurring rental income
- Potential long-term property appreciation
- Gradual equity growth through mortgage principal repayment
- Flexibility to retain or eventually sell the property
Important considerations:
- Vacancy and tenant turnover
- Maintenance and unexpected repairs
- Landlord responsibilities and legal requirements
- Financing costs and cash flow variability
Who might consider this strategy?
Someone interested in longer-term property ownership who has the financial resources to manage ongoing expenses, potential vacancies, and unexpected repairs.
2. Multifamily Properties: Multiple Units, Multiple Considerations
Multifamily investing involves purchasing a property containing more than one residential unit, such as a duplex, triplex, or fourplex.
Unlike a single-family rental, a multifamily property may generate income from several households within one building.
That can create opportunities for multiple rental income streams. For example, if one unit becomes vacant, rental income from other occupied units may help offset expenses.
However, multiple units also mean multiple tenants, potentially more maintenance, and additional operational responsibilities.
Financing, insurance, property taxes, and management requirements can differ depending on the property’s size, configuration, and intended occupancy.
It’s also important to recognize that multifamily investing isn’t necessarily a separate strategy from long-term rental ownership. A duplex purchased as a long-term rental is both a multifamily property and a buy-and-hold investment.
Potential advantages:
- Multiple potential sources of rental income
- Opportunity to spread vacancy exposure across several units
- Potential operating efficiencies when units share a property
- Flexibility for certain owner-occupied arrangements
Important considerations:
- Multiple tenant relationships
- Maintenance of shared structures and systems
- Property-specific financing and insurance requirements
- Higher acquisition costs in some markets
Who might consider this strategy?
An investor interested in rental income from multiple units who is comfortable with the added responsibilities of managing a multifamily property.
3. Fix-and-Flip Properties: Investing Through Improvements
Fix-and-flip investing takes a different approach.
Rather than purchasing property primarily for ongoing rental income, an investor acquires a home with the intention of improving it and reselling it.
The opportunity generally lies in purchasing at an appropriate price, completing improvements efficiently, and selling for enough to cover the entire investment while producing a profit.
And that last part is where careful analysis becomes essential.
The purchase price and renovation budget are only part of the equation. Investors must also consider financing, property taxes, insurance, utilities, permits, contractor expenses, carrying costs, selling expenses, and the possibility of unexpected repairs.
Market conditions can also change between acquisition and resale.
A beautifully renovated property isn’t automatically a profitable investment.
Potential advantages:
- Opportunity to create value through improvements
- Potential profit without long-term tenant management
- A defined project-oriented investment approach
- Opportunities to improve properties that need attention
Important considerations:
- Renovation costs and unforeseen conditions
- Contractor availability and project delays
- Financing and carrying expenses
- Resale pricing and changing market conditions
Who might consider this strategy?
Someone with access to sufficient capital, a realistic understanding of renovation costs, reliable professional resources, and the financial capacity to manage delays or unexpected expenses.
4. Short-Term Rentals: A More Active Investment Model
Short-term rental investing generally involves offering furnished residential properties for stays shorter than traditional residential leases.
Depending on the property and location, guests might include vacationers, business travelers, or people seeking temporary accommodations.
These investments can offer flexibility in pricing and property use, but they frequently involve more active management than traditional long-term rentals.
Guest communication, cleaning, furnishing, maintenance, marketing, and frequent turnover all affect the operation.
Income may also fluctuate considerably based on seasonality, local demand, competition, and occupancy.
And perhaps most importantly, short-term rental use isn’t automatically permitted simply because a property is residential.
Local zoning, licensing requirements, homeowners association restrictions, taxes, and other regulations must be evaluated before purchasing a property for this purpose.
Potential advantages:
- Flexibility in rental pricing and availability
- Potential to serve different types of guests
- Opportunities in markets with consistent short-term accommodation demand
- Greater control over rental periods, subject to applicable restrictions
Important considerations:
- Local regulations and property restrictions
- Variable occupancy and seasonal demand
- Furnishing, cleaning, and guest management expenses
- Higher operational involvement and potentially unpredictable income
Who might consider this strategy?
An investor comfortable operating a more hands-on property business, or budgeting for professional management, who understands the importance of local demand and regulatory compliance.
5. House Hacking: Combining Homeownership and Investment
House hacking is a strategy that combines a primary residence with an income-producing opportunity.
A common example involves purchasing a duplex, living in one unit, and renting the other.
Depending on the property and applicable regulations, other arrangements might include renting a permitted accessory dwelling unit or part of a primary residence.
The objective is often to use rental income to help offset ownership expenses while building equity in a property.
For some buyers, this can create a different entry point into real estate investing because the property also serves as their home.
However, owner occupancy doesn’t eliminate the financial and legal responsibilities associated with renting property.
Buyers must evaluate financing requirements, property configuration, rental restrictions, privacy, tenant relationships, and whether they can comfortably afford the property without relying on uninterrupted rental income.
Potential advantages:
- Opportunity to offset a portion of housing expenses
- Potential to build equity while occupying the property
- Experience with rental property ownership
- Possibility of transitioning to a fully rented property later, subject to financing and other requirements
Important considerations:
- Sharing a property with tenants
- Financing and owner-occupancy requirements
- Local zoning and rental regulations
- Financial exposure during vacancies or nonpayment
Who might consider this strategy?
A buyer interested in combining homeownership with rental income who is comfortable with the practical realities of living near tenants and managing an income-producing property.
How Do These Investment Strategies Compare?
Although these five approaches are often discussed separately, they aren’t mutually exclusive.
A multifamily property can be a long-term rental investment. A duplex can support a house-hacking strategy. A property originally purchased for renovation and resale might ultimately be retained as a rental if the owner’s circumstances and financial analysis support that decision.
The more meaningful distinction is often what you’re trying to accomplish and what you’re prepared to manage.
| Investment Strategy | Primary Financial Objective | Typical Ownership Involvement | Key Consideration |
|---|---|---|---|
| Long-term rental | Recurring income and potential appreciation | Ongoing | Tenant management, maintenance, and vacancies |
| Multifamily property | Income from multiple residential units | Ongoing | Multiple tenants, operating costs, and property complexity |
| Fix-and-flip | Potential profit through renovation and resale | Intensive during project | Renovation costs, timing, and resale risk |
| Short-term rental | Income from shorter guest stays | Often highly active | Occupancy, regulations, and operating expenses |
| House hacking | Offset personal housing expenses while building equity | Ongoing and personal | Owner occupancy, tenant relationships, and financing |
These are general comparisons, not predictions of investment performance. Actual returns, expenses, and management requirements depend on the individual property and circumstances.
What About Other Types of Real Estate Investments?
Residential rental and renovation strategies are only part of the larger real estate investment landscape. Investors may also explore undeveloped land, commercial properties such as retail, office, industrial, and mixed-use buildings, or indirect investment opportunities through Real Estate Investment Trusts (REITs), syndications, and crowdfunding platforms. These options involve different ownership structures, financing considerations, levels of participation, liquidity, and risk. Understanding the broader range of opportunities can help investors evaluate which direction best aligns with their objectives.
Regardless of the investment strategy, understanding applicable Fair Housing laws and other legal obligations is an essential part of responsible real estate ownership. Federal, state, and local requirements can affect how properties are marketed, how prospective occupants are evaluated, and how housing-related decisions are made. Specific obligations vary by property type, intended use, and circumstances, making it important to consult qualified professionals and understand the applicable requirements before proceeding.
Five Questions to Ask Before Choosing an Investment Strategy
Before evaluating individual properties, it helps to understand what you want the investment to accomplish.
1. Am I looking for ongoing income, long-term appreciation, or a shorter-term opportunity?
A long-term rental property and a fix-and-flip project may both involve purchasing residential real estate, but their financial objectives and timelines can be very different.
Understanding your priorities helps narrow the possibilities.
2. How much capital can I comfortably commit?
The purchase price is only the beginning.
Down payments, closing costs, financing, reserves, repairs, improvements, and unexpected expenses all influence how much capital an investment may require.
An opportunity should be evaluated against your complete financial picture, not simply the amount needed to acquire the property.
3. How involved do I want to be?
Some strategies require substantial hands-on participation, but that doesn’t necessarily mean investors need to manage every detail themselves.
Depending on the property and investment strategy, certain responsibilities may be delegated to property managers, contractors, or other qualified professionals. For fix-and-flip projects, I can also assist with coordinating property improvements and design, preparing the home for market, and managing the resale process when appropriate.
These arrangements involve different costs, responsibilities, and levels of oversight, so it’s important to understand exactly what services are being provided and what decisions remain yours.
Consider how the investment fits into your lifestyle, availability, and interests—and what professional support might make the process more manageable.
4. What risks am I prepared to manage?
Vacancies, unexpected repairs, market fluctuations, financing costs, regulatory changes, and renovation overruns can all affect an investment.
Different strategies introduce different types of exposure.
The goal isn’t to find an investment without risk. It’s to understand the risks before making a commitment.
5. What’s my long-term plan for the property?
Will you hold the property for years? Sell after renovations? Eventually convert an owner-occupied property into a rental?
And what happens if your circumstances change?
Considering your potential exit strategies before purchasing can help you evaluate whether a particular investment offers the flexibility you may need.
The Right Investment Starts With the Right Questions
There isn’t one residential real estate investment strategy that’s universally better than the others.
A property that makes financial sense for an experienced investor with substantial reserves and established contractor relationships may not be appropriate for someone purchasing their first investment.
Similarly, an investor seeking predictable long-term ownership may approach opportunities very differently from someone interested in renovation and resale.
The objective isn’t simply to find a property that looks like a good investment. It’s to determine whether the property, the strategy, and the financial realities align with your goals.
For a broader introduction to evaluating your first investment purchase, you can also explore Investing 101: What You Need to Know Before You Buy Your First Investment Property.
Whether you’re considering a rental property, exploring a multifamily opportunity, or wondering how real estate investing might fit into your longer-term plans, thoughtful research and realistic financial analysis are essential.
As a Realtor® serving buyers and sellers throughout Virginia and West Virginia, I believe the most valuable starting point is understanding your objectives, exploring your options, and evaluating the opportunities and challenges before making a decision.
Your Goals. Strategic Guidance. Confident Decisions.
This article is intended for general educational purposes and does not constitute financial, tax, legal, or investment advice. Consult appropriately qualified professionals regarding your individual circumstances.
Frequently Asked Questions
What is the difference between a rental property and an investment property?
A rental property is one type of investment property, generally purchased or held to generate income from tenants. Investment properties can also include properties acquired for renovation and resale or other investment purposes. Not every investment property is operated as a rental.
Is a single-family home or multifamily property better for investing?
Neither is automatically better. Single-family rentals and multifamily properties differ in acquisition costs, financing, tenant management, maintenance, and income potential. The better fit depends on the property’s financial performance, the investor’s resources, and their objectives.
Can I invest in real estate while living in the property?
Yes. Certain owner-occupied arrangements, commonly described as house hacking, allow buyers to live in a property while renting another unit or permitted portion. Financing, zoning, occupancy, and rental requirements must be evaluated for the specific property.
Are short-term rentals more profitable than long-term rentals?
Not necessarily. Short-term rentals may generate higher gross revenue in some markets, but they can also involve greater operating expenses, fluctuating occupancy, and more active management. Net income and risk matter more than advertised nightly rates.
Do I need a large amount of money to start investing in residential real estate?
Capital requirements vary considerably depending on the property, financing structure, occupancy plans, and investment strategy. Beyond the initial purchase, investors should consider reserves for repairs, vacancies, operating expenses, and unexpected costs.
Should I buy an investment property before or after purchasing my primary residence?
There isn’t a universal answer. Financing qualifications, available capital, personal housing needs, debt obligations, and long-term objectives all influence that decision. Evaluating both options with qualified lending and financial professionals can help clarify the implications.